Does Commercial Property Insurance Cover Equipment Failure? What North Carolina Businesses Should Review
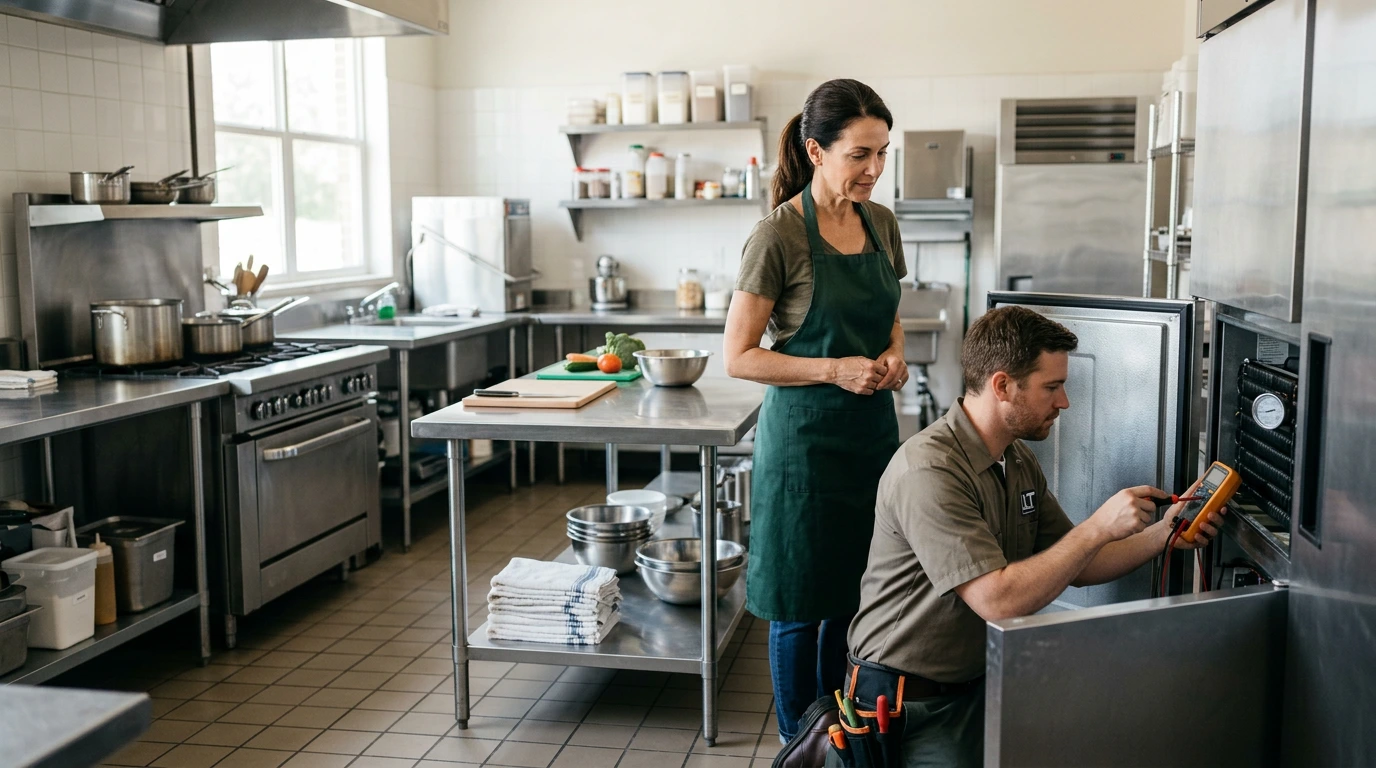
A restaurant refrigerator stops cooling overnight. An HVAC system fails during a busy week. A manufacturing machine goes down without warning. The immediate question is usually simple: “Is this covered?” The answer is rarely simple.
Commercial property insurance and equipment breakdown coverage can address different types of loss. A property policy may respond to certain covered causes of physical damage, such as fire or wind. Equipment breakdown coverage is designed to address certain sudden and accidental breakdowns involving covered equipment, subject to the policy’s terms and exclusions.
For a North Carolina business, the important step is to understand the difference before the equipment failure turns into lost sales, spoiled inventory, delayed work, or an unhappy customer list.
Quick answer: Commercial property insurance may cover physical loss from covered causes such as fire or storm damage. Equipment breakdown coverage may address certain mechanical, electrical, pressure, or computer-related breakdowns. Coverage depends on the policy, cause of loss, limits, endorsements, and exclusions.
Why property insurance may not cover every equipment failure
Commercial property insurance is often built around named or specified causes of loss. If a fire damages a commercial oven, property insurance may be relevant. If wind damages an exterior HVAC unit, that may also trigger a property-coverage discussion.
But a machine that stops working because of an internal mechanical or electrical failure may not be treated the same way. Wear and tear, maintenance issues, corrosion, and gradual deterioration may also be excluded or limited.
This is why business owners should not assume that “property coverage” automatically means “repair coverage for every broken machine.”
Learn about commercial building and property insurance.
What equipment breakdown coverage is intended to address
Equipment breakdown coverage may help with certain losses caused by a covered breakdown of equipment such as:
- Electrical panels and wiring
- HVAC systems and refrigeration equipment
- Boilers and pressure systems
- Computers, networks, and electronic systems
- Manufacturing or production equipment
- Certain kitchen and food-service equipment
The exact list depends on the policy. So does the definition of “breakdown.” A good conversation focuses on the equipment the business cannot afford to lose, rather than assuming every item is automatically included.
Review equipment breakdown insurance options from Laurie Insurance Group.
The real cost is often bigger than the repair
When equipment fails, repair or replacement cost is only part of the problem. A restaurant may lose perishable inventory and miss an entire weekend of service. A medical office may need to reschedule appointments. A manufacturer may lose production time. A retail store may face a hot, uncomfortable space while waiting on HVAC repairs.
Depending on the policy, equipment breakdown coverage may also include certain related expenses, such as spoiled inventory, business-income loss, or extra expense. Those extensions are not automatic, which is why limits and endorsements matter.
Property loss versus equipment breakdown
| Scenario | Coverage that may be relevant |
|---|---|
| A fire damages a commercial refrigerator | Commercial property insurance may be relevant |
| A power surge damages electronic equipment | Equipment breakdown may be relevant |
| A storm damages rooftop HVAC equipment | Commercial property insurance may be relevant |
| Internal electrical failure shuts down a machine | Equipment breakdown may be relevant |
| Gradual wear and maintenance neglect cause failure | May be excluded or limited |
The same piece of equipment can be involved in very different claims. What matters is the cause of the loss and the specific coverage purchased.
Which businesses should pay attention?
Nearly every business depends on equipment, but some operations have especially high exposure:
- Restaurants, bakeries, and food-service businesses
- Medical, dental, and veterinary practices
- Manufacturers and fabrication shops
- Hotels and property managers
- Retailers with refrigeration or climate-control needs
- Offices that rely on servers, networks, and computer systems
- Contractors with specialized equipment
A useful question is: if this equipment stopped working today, what would it cost the business by the end of the week?
What to review before a breakdown happens
An annual policy review should include more than the building value. Make a list of the systems and machines that keep the business operating.
Ask:
- Which equipment would interrupt operations if it failed?
- Does the policy include equipment breakdown coverage, or is it an optional endorsement?
- Are spoilage, business income, and extra expenses included?
- Are the limits high enough for replacement costs and the resulting interruption?
- Does the business have a maintenance and service-record process?
- Have new systems, refrigeration units, production machines, or computer systems been added since the policy was written?
A simple example
A small North Carolina restaurant relies on one walk-in cooler, several refrigeration units, and a commercial ice machine. A sudden electrical failure damages the cooler’s control system. The owner faces a repair bill, spoiled food, and a short-term closure while the kitchen is stabilized.
The building did not burn and no storm damaged the property. The loss may still involve equipment breakdown coverage, depending on the policy. That is why the owner should review the coverage before the failure—not while trying to salvage inventory.
Protect the systems that keep your business moving
Laurie Insurance Group can help North Carolina business owners review commercial property and equipment breakdown coverage in light of their actual equipment, operations, and downtime exposure.
Contact Laurie Insurance Group to discuss equipment breakdown coverage for your business.
Contact Us!
For quotes or questions, fill out the form below and one of our agents will be in touch shortly!